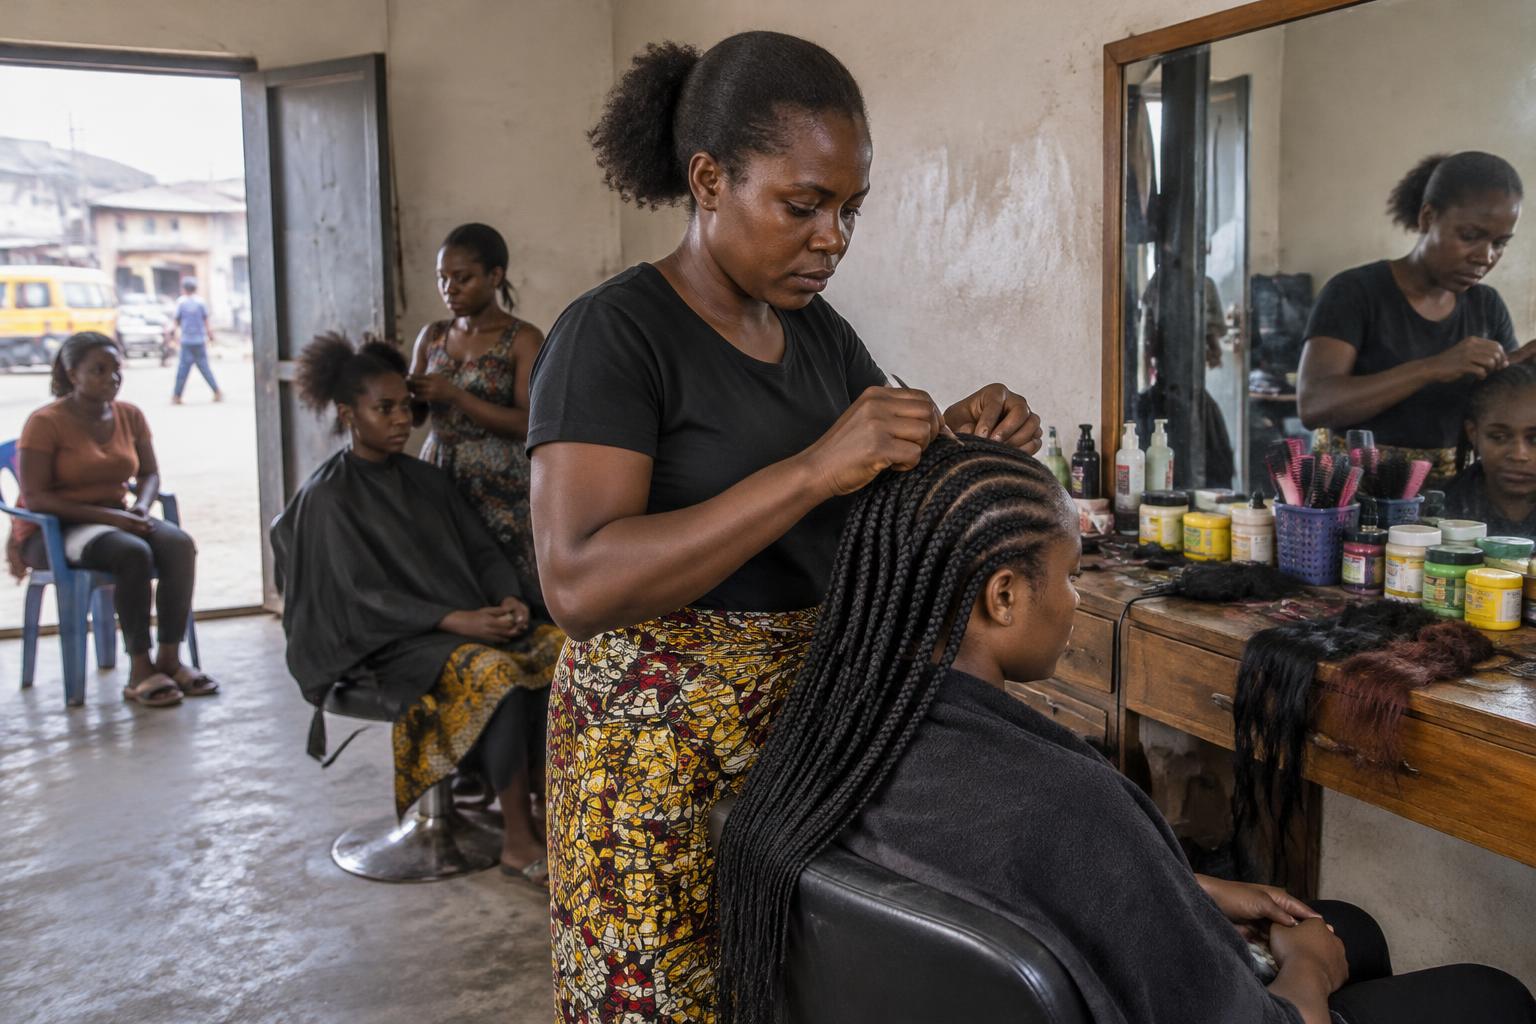
“I’ll pay you at the end of the month.” Every service provider knows this sentence. A hairdresser completes braids worth 40,000 CDF, buys hair extensions, pays for transport—and sometimes goes home with nothing in her pocket.
The trap of financing the work upfront
When a service is provided entirely on credit, the entrepreneur is effectively financing her customer. She pays the direct costs upfront—transport, hair extensions and supplies—and carries all the risk. Multiply that by ten customers, and cash can run out even while the business appears to be thriving.
A deposit as a clear ground rule
Asking for a deposit is not a sign of distrust. It is a clear rule, communicated in advance, that protects both parties:
- The deposit should cover at least the direct costs incurred.
- The outstanding balance is recorded immediately as Accounts Receivable / Due.
- The customer knows exactly how much she still owes.
In the braiding example, the service is worth 40,000 CDF, the deposit is 10,000 CDF, and direct costs are 9,000 CDF. The deposit covers those costs from day one, while the remaining 30,000 CDF is tracked until payment.
Follow up with confidence
A properly recorded customer balance is easier to follow up on. With a date, an exact amount and the customer’s history, a follow-up becomes a straightforward reminder rather than a conflict. When payment arrives, the balance is collected without creating a second sale: Revenue remains accurate.
What changes for the entrepreneur
More stable cash flow, less stress and a clearer view of what each service contributes. Making a deposit standard is often the first habit that helps turn a fragile activity into a stronger business.